
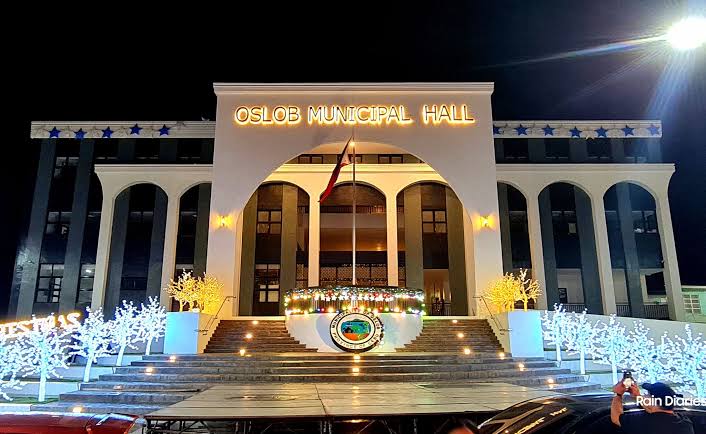
Incomplete travel records and missing fuel consumption reports have prevented auditors from determining whether Oslob’s spending on gasoline and diesel for government vehicles was reasonable, the Commission on Audit (COA) said.
In its 2025 Annual Audit Report, COA flagged deficiencies in the municipality’s monitoring and documentation of fuel use, warning that the lapses could lead to “wasteful spending of government funds.”
Auditors found that the local government unit (LGU) failed to prepare and submit monthly reports on official travels and fuel consumption for examination.
They also found that drivers’ trip tickets lacked essential details, including beginning and ending odometer readings, passenger lists, fuel consumed, and departure and arrival times.
The deficiencies raised concerns about the municipality’s internal controls over fuel procurement and the use of government vehicles, according to the report.
During the audit, the municipal engineering staff confirmed that the LGU had no other records for monitoring and accounting for fuel consumption apart from trip tickets issued by the Office of the Mayor.
However, COA Circular No. 77-61, dated Sept. 26, 1977, requires government agencies to maintain documentation systems to control government vehicle use and prevent excessive or unnecessary fuel expenses.
Under the rules, drivers must obtain authorization before official trips and use properly accomplished, approved and serially numbered trip tickets.
Government offices must also prepare a Monthly Report of Official Travels, listing trips in chronological order, and a Monthly Report of Fuel Consumption detailing the vehicles used, distances traveled, fuel consumed and normal consumption rates. Oslob did not submit either report for audit evaluation, COA said.
Auditors also found that disbursement vouchers for gasoline and diesel payments lacked Requisition and Issue Vouchers (RIVs) and summaries of daily fuel issuances based on those vouchers.
Instead, the payment documents were supported only by drivers’ trip tickets, suppliers’ sales invoices issued during refueling and statements of account submitted during billing.
The missing records limited auditors’ ability to verify whether the fuel purchased was properly issued, used for official purposes and consistent with the municipality’s actual transportation requirements.
COA cited Section 4(6) of Presidential Decree No. 1445, which requires claims against government funds to be supported by complete documentation.
In response, the concerned office agreed to ensure that trip tickets would be properly completed for all official travel. The General Services Office also committed to preparing and submitting the required monthly reports at the end of each month.
The Accounting Office, meanwhile, agreed to strictly require RIVs and summaries of daily fuel issuances before processing payments for fuel and oil.

Comments